
John Healey announced in the October 2026 budget that the trading allowance was increasing from £1000 to £3000 per annum with effect from April 2027.
Category Archives: UK Budget
New Pension Tax Allowance in 2027
John Healey announced in his recent budget that there would be an additional allowance for pensioners whose income was up to the level of the basic state pension but higher than the personal allowance of £12,570.
This additional personal allowance had been mooted since the increase in the basic state pension for 2027 had been confirmed to be over the level of the personal allowance. Andy Burnham had said that pensioners who purely relied on the basic state pension would not have to pay tax, but it was just the mechanism of how this would be done that was confirmed in the budget.
The allowance has actually been extended to include any income, as long as it is under the new basic state pension of £13,036.40. So, for example, if you have a state pension of £10,000 pa but a private pension of £3,000 pa then you would still get the extra allowance.
If your income is slightly higher than £13,037 then there will be some taper relief so that you will not be suddenly dropped back to £12,570 and then be worse off than if you earned less. So if your income is between £13,037 and £13,319 then you will receive some pension tax allowance.
For every £3 of income above the level of the basic state pension (i.e. £13,037 for 2027/28), your pension tax allowance will reduce by £1, so by the time you earn £13,319 you will not get any additional allowance and your personal allowance will be £12,570.
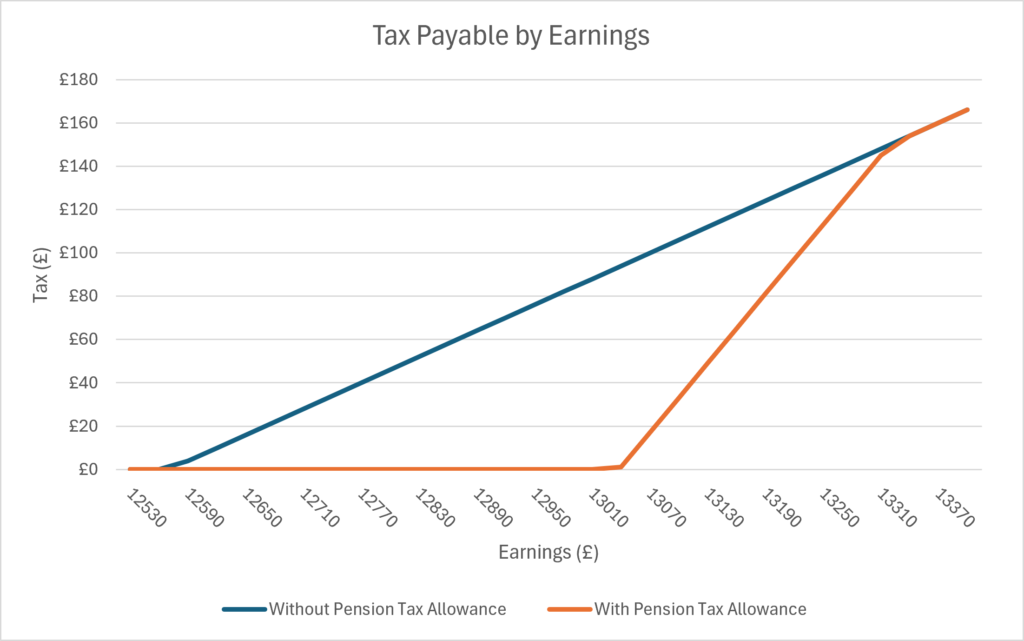
This calculation is confusing in my mind and does not match up with the way taper relief works for those earning over £100,000. In the case of the Pension Tax Allowance, the reduction only matches up to the amount of tax saved and not the actual tax allowance as I would describe it.
Although the amount of earnings that you can now have without paying tax has been increased by £467, they have not called this the pension tax allowance. Instead, they have called the PTA £94, which is the amount of tax saved (467 x 20%). So you only get taper relief if your earnings are 3 x the amount of tax saved (3 x 94 = 282 plus the £13,037 = £13,319).
Contrast this to the taper relief on earnings over £100k which reduces the personal allowance by £1 for every £2 earned over that, so when you get to £125,140 (2 x 12,570 +100,000) you lose the personal allowance.
So why is the taper relief threshold not 3 x 467 + 13,037 = £14,438? I would love an explanation to this so if you know please comment as this is an opinion piece.
The value of the pension tax allowance will increase in line with the basic state pension each year.
The fact that the pension tax allowance has been introduced does imply that the government is not planning on increasing the personal allowance at any time soon. It is currently set to remain at £12,570 until the end of the 2030/31 tax year so I think we shouldn’t expect any changes until after that date.
Capital Gains Tax Changes from 2023
 In the Autumn Statement from the Chancellor of the Exchequer, Jeremy Hunt, today (17th November 2022), it was announced that the capital gains tax (CGT) allowance was being reduced with effect from next year.
Higher Rate Tax Bracket Changed
 The Chancellor of the Exchequer, Jeremy Hunt, has announced in his Autumn Statement today, 17th November 2022 (otherwise known as the autumn budget) that the higher rate tax bracket would change – that is, the level at which people start paying the top rate of 45% tax will change to £125,140. Continue reading Higher Rate Tax Bracket Changed
Personal Allowance Freeze for 5 Years

In the budget today (3rd March 2021) the Chancellor of the Exchequer, Rishi Sunak, confirmed the the personal allowance for 2021/22 would increase to £12,570 as had previously been confirmed.
However, he also confirmed that, in order to start to claw back some of the massive spending that needed to happen in order to finance payments during the coronavirus pandemic, the personal allowance would remain frozen at that level until April 2026.
The personal allowance is the amount of money that can be earned before tax is paid. Once the level is passed, anyone who earns over £12,570 will need to pay tax at 20% for the amount of earnings between the personal allowance and the higher rate tax bracket.
In addition to this, the 40% tax bracket starting point, which will be increased slightly to £52,270 on 6th April 2021, will also be frozen for 5 years and will not be increased until at least 2026.
This means that as people start to see pay rises over the coming years, they may be pushed into a situation where they pay more tax or move into a higher tax bracket.
This announcement came alongside confirmation that the furlough scheme will be extended as will the SEISS scheme for the self-employed, plus there will be an extra £20 a week for those on Universal Credit and Working Tax Credit for the first 6 months of the 2021/22 tax year.
The stamp duty holiday will also be extended to the end of June with a partial amount also being available until the end of September.
The Capital Gains Tax allowance was also included in the budget and it was confirmed that this would increase to £12,300 for the tax year 2021/22 and then also remain at that level for 5 years until 2026.
Capital Gains Tax (CGT) Allowance 2019/20
The Capital Gains Tax (CGT) annual exempt amount is the amount of gains that you are allowed to make before paying tax on those profits.
Capital Gains Tax is paid when you sell or dispose of assets such as personal possessions worth more than £6,000, property that is not your main home, shares or business assets.
CGT is based on the amount of profit that you have made, not on the selling price.
Each year the CGT annual exempt allowance is increased in line with the rise in the Consumer Prices Index, rounded up to the next £100.
In 2018/19 the CGT allowance was £11,700.
In 2019/20 this will be increasing to £12,000.
The law also provides that the annual exempt amount available to most trustees of settlements is one half that due to individuals and so this will be £6,000 for the tax year 2019/20.
For details of all current tax rates that we monitor, please see this page.
2019 Personal Allowance

In the 2019 Budget today Philip Hammond announced changes to the personal allowance for 2019/20.
It had previously been announced that the plan was to increase the tax free personal allowance to £12,500 and the higher rate allowance threshold to £50,000 from April 2020.
There had been rumours prior to the budget that the Chancellor would have to delay the increase in the personal allowance in order to fund increases to the NHS.
Mr Hammond commented on this himself and said that he had been advised that the least painful way to add some funding to the NHS promises was to do exactly that.
However, he also said that this was not his idea of ending austerity (which was part of the budget headlines) and so he would not be doing that. In fact, he said, he would actually bring forward the increases in the personal allowance levels by a year and implement those increases from April 2019 instead of April 2020.
So the personal allowance from April 2019 will be £12,500 which is increased from £11,850 for 2018/19, an increase of £650 and a saving of £130 a year for basic rate taxpayers.
Personal Allowance 2018/19

Budget 2017
The Chancellor Philip Hammond has announced in his 2017 Budget today that the UK personal allowance 2018/19 will increase with effect from April 2018 to £11,850.
This is the amount that people can earn before having to pay any tax on earnings above that level.
An increase of £350 in the personal allowance means an extra £70 a year (or £5.83 a month) in the pocket of a basic rate tax payer.
Currently the personal allowance sits at £11,500 for the year 2017/18 and so this is an increase of 3.04%.
The eventual aim that has been proposed by the government is to get the personal allowance to £12,500 a year.
The higher rate tax bracket will also be increase from £45,000 to £46,350. The aim is for this to be increased eventually to £50,000.
You can find all of the current personal allowance rates in the tables on this page (these will be updated as they are announced).
Also announced in the Budget today was the increase in the National Minimum Wage of 4.4%, rising from £7.50 an hour to £7.83 an hour with effect from April 2018.
October 2018 Update
Check out the change to the personal allowance for 2019/2020 here.
Personal Allowance Increased for 2017/18
The Chancellor of the Exchequer, George Osborne, today announced in his March 2016 Budget an increase in the personal allowance for 2017/18 which for 2016/17 stands at £11,000.
The personal allowance for 2017/18 has been set at £11,500 which is an increase of 4.5% over the previous year. This increase is to keep in line with the plan that the Conservative Party announced in the election manifesto to increase the personal allowance by the end of their term to £12,500.
This single level personal allowance now applies to people of all ages, including those over 75, as the age allowance for pensioners has been removed so that everyone is entitled to the same personal allowance.
New Dividend Tax Introduced in 2015 Budget
In recent years there have been a lot of changes to personal allowances and indeed other allowances that affect personal income. Not only has the personal allowance increased significantly and more recently a tax free savings allowance was introduced, now there is another change to the tax charged on dividend payments to individuals.
The changes are a little bit complex and will affect quite a lot of people receiving dividend income, and not always for the better.
There is a new allowance of £5,000 per person per year on dividends which is tax free, but any dividend income over this amount will be taxed at a higher rate than previously, depending on the tax bracket of the individual.
A basic rate tax payer will need to pay 7.5% tax on amounts over £5,000, a higher rate tax payer will need to pay 32.5% and an additional rate tax payer will need to pay 38.1%.
These rates are effective from April 1016.
It may be useful to note that the new £5,000 savings tax free rate is in addition to this (for those who have low enough incomes) and so it may be worth getting some advice as to whether some shares should be switched to a different investment vehicle to minimise tax.