
John Healey announced in the October 2026 budget that the trading allowance was increasing from £1000 to £3000 per annum with effect from April 2027.
Category Archives: Tax Allowances
New Pension Tax Allowance in 2027
John Healey announced in his recent budget that there would be an additional allowance for pensioners whose income was up to the level of the basic state pension but higher than the personal allowance of £12,570.
This additional personal allowance had been mooted since the increase in the basic state pension for 2027 had been confirmed to be over the level of the personal allowance. Andy Burnham had said that pensioners who purely relied on the basic state pension would not have to pay tax, but it was just the mechanism of how this would be done that was confirmed in the budget.
The allowance has actually been extended to include any income, as long as it is under the new basic state pension of £13,036.40. So, for example, if you have a state pension of £10,000 pa but a private pension of £3,000 pa then you would still get the extra allowance.
If your income is slightly higher than £13,037 then there will be some taper relief so that you will not be suddenly dropped back to £12,570 and then be worse off than if you earned less. So if your income is between £13,037 and £13,319 then you will receive some pension tax allowance.
For every £3 of income above the level of the basic state pension (i.e. £13,037 for 2027/28), your pension tax allowance will reduce by £1, so by the time you earn £13,319 you will not get any additional allowance and your personal allowance will be £12,570.
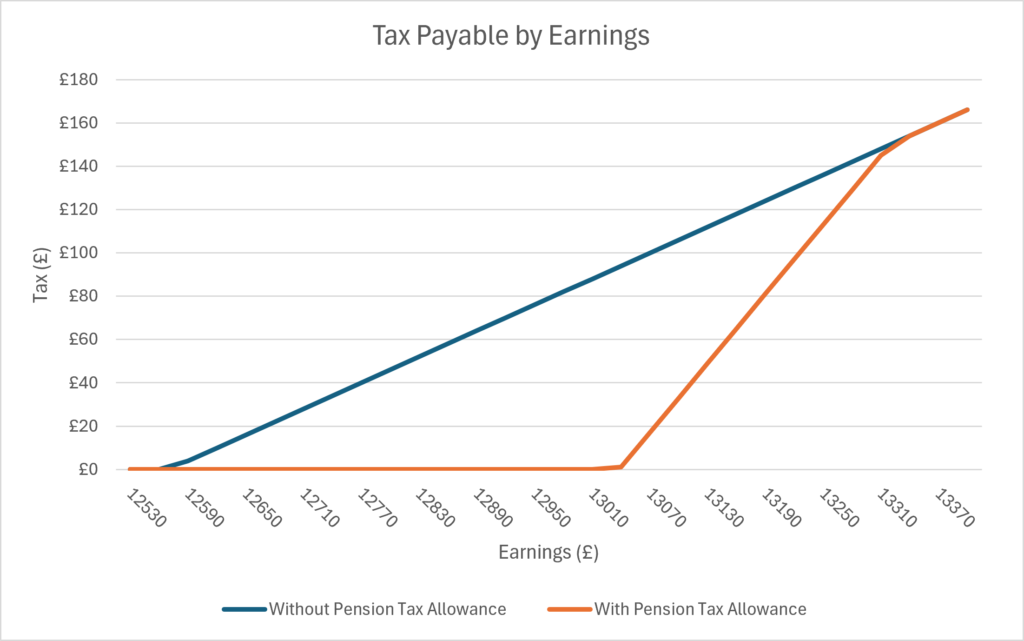
This calculation is confusing in my mind and does not match up with the way taper relief works for those earning over £100,000. In the case of the Pension Tax Allowance, the reduction only matches up to the amount of tax saved and not the actual tax allowance as I would describe it.
Although the amount of earnings that you can now have without paying tax has been increased by £467, they have not called this the pension tax allowance. Instead, they have called the PTA £94, which is the amount of tax saved (467 x 20%). So you only get taper relief if your earnings are 3 x the amount of tax saved (3 x 94 = 282 plus the £13,037 = £13,319).
Contrast this to the taper relief on earnings over £100k which reduces the personal allowance by £1 for every £2 earned over that, so when you get to £125,140 (2 x 12,570 +100,000) you lose the personal allowance.
So why is the taper relief threshold not 3 x 467 + 13,037 = £14,438? I would love an explanation to this so if you know please comment as this is an opinion piece.
The value of the pension tax allowance will increase in line with the basic state pension each year.
The fact that the pension tax allowance has been introduced does imply that the government is not planning on increasing the personal allowance at any time soon. It is currently set to remain at £12,570 until the end of the 2030/31 tax year so I think we shouldn’t expect any changes until after that date.
What is the Personal Allowance for 2025/26?
 As you may well be aware, the personal allowance (the amount that you are able to earn before being taxed) has remained static for a number of years and has caused what is known as fiscal drag, bringing more people into the tax paying brackets.
Continue reading What is the Personal Allowance for 2025/26?
Personal Allowance 2023/24
 The personal allowance is the amount that you can earn either through working or via a pension payment before you start to pay tax.
The personal allowance for 2023/24 is the subject of much debate due to the increase in the rate of the state pension and also of earnings, because the personal allowance is not increasing from the 2022/23 rate. Continue reading Personal Allowance 2023/24
Higher Rate Tax Bracket Changed
 The Chancellor of the Exchequer, Jeremy Hunt, has announced in his Autumn Statement today, 17th November 2022 (otherwise known as the autumn budget) that the higher rate tax bracket would change – that is, the level at which people start paying the top rate of 45% tax will change to £125,140. Continue reading Higher Rate Tax Bracket Changed
Jeremy Hunt Reverses Tax Changes
 In the current political turmoil there were always going to be more changes coming after the mini budget and the sacking of ex-Chancellor Kwasi Kwarteng last week.
With Jeremy Hunt’s appointment as the new Chancellor it seemed imperative to make some changes that settled the financial markets and these came swiftly after his appointment, instead of on 31st October as previously promised.
The main change that affects the information that this website provides is the reversal of the 1% drop in the lower rate of income tax that was due to come into effect in April next year.
The lower rate was due to drop from 20% to 19% for earnings over the personal allowance of £12,570 and below £50,270, but this has now been scrapped and the lower rate will remain at 20% for the foreseeable future.
The scrapping of the higher rate of 45% had already been almost immediately reversed and so that will also now stay the same as before.
The scrapping of the increase in National Insurance payments does remain however so that is one thing left from the mini budget.
We will be keeping a check on any further announcements to see if more tax changes are in store.
U-Turn on 45p Tax Rate Cut
 It is being reported today that the 45p tax rate cut that was announced in the mini-budget 10 days ago is now going to be scrapped due to the lack of support from the Conservative back benchers. Continue reading U-Turn on 45p Tax Rate Cut
Is the Personal Allowance Increasing in 2023?
 The personal allowance is the amount that you can earn each year before you are subject to tax. It has remained pretty static in the last few years but is the personal allowance increasing in 2023?
Continue reading Is the Personal Allowance Increasing in 2023?
Tax Rates for 2022/23
 As we start a new tax year in 2022/23 we are often faced with new tax and personal allowance rates which might mean that we have more take home pay. However, this year, there are not many changes to tax rates and no change to the personal allowance which remains at £12,570.
Which Tax Allowances Changed for 2021/22?
 Due to the current economic situation the planned changes to some allowances for 2021/22 have not happened or have been slightly revised. So which tax allowances have changed for this year?
Not many allowances have changed this year and those that have changed have only done so by a small amount.
Capital Gains Tax (CGT), Inheritance Tax (IHT), the annual ISA Allowance and the Personal Savings Allowance are examples of some tax allowances that have not changed between 2020/21 and 2021/22.
You can see all of the current rates, including the rates from previous years, on the allowances page here.
The two main tax rates that have changed are the personal allowance and the personal tax rates (although these are intrinsically linked so could be counted as one).
The personal allowance has increased to £12,570 from £12,500 – so only a small increase – and the higher rate tax bracket now starts at £50,270 instead of £50,000.
Some allowances are also set to be frozen until 2026 so that some of the debt that has been built up over the last year can be recouped. Therefore, as people earn more, they may find that they are paying more tax.
It may be a while until we see a sustained increase in tax allowances.